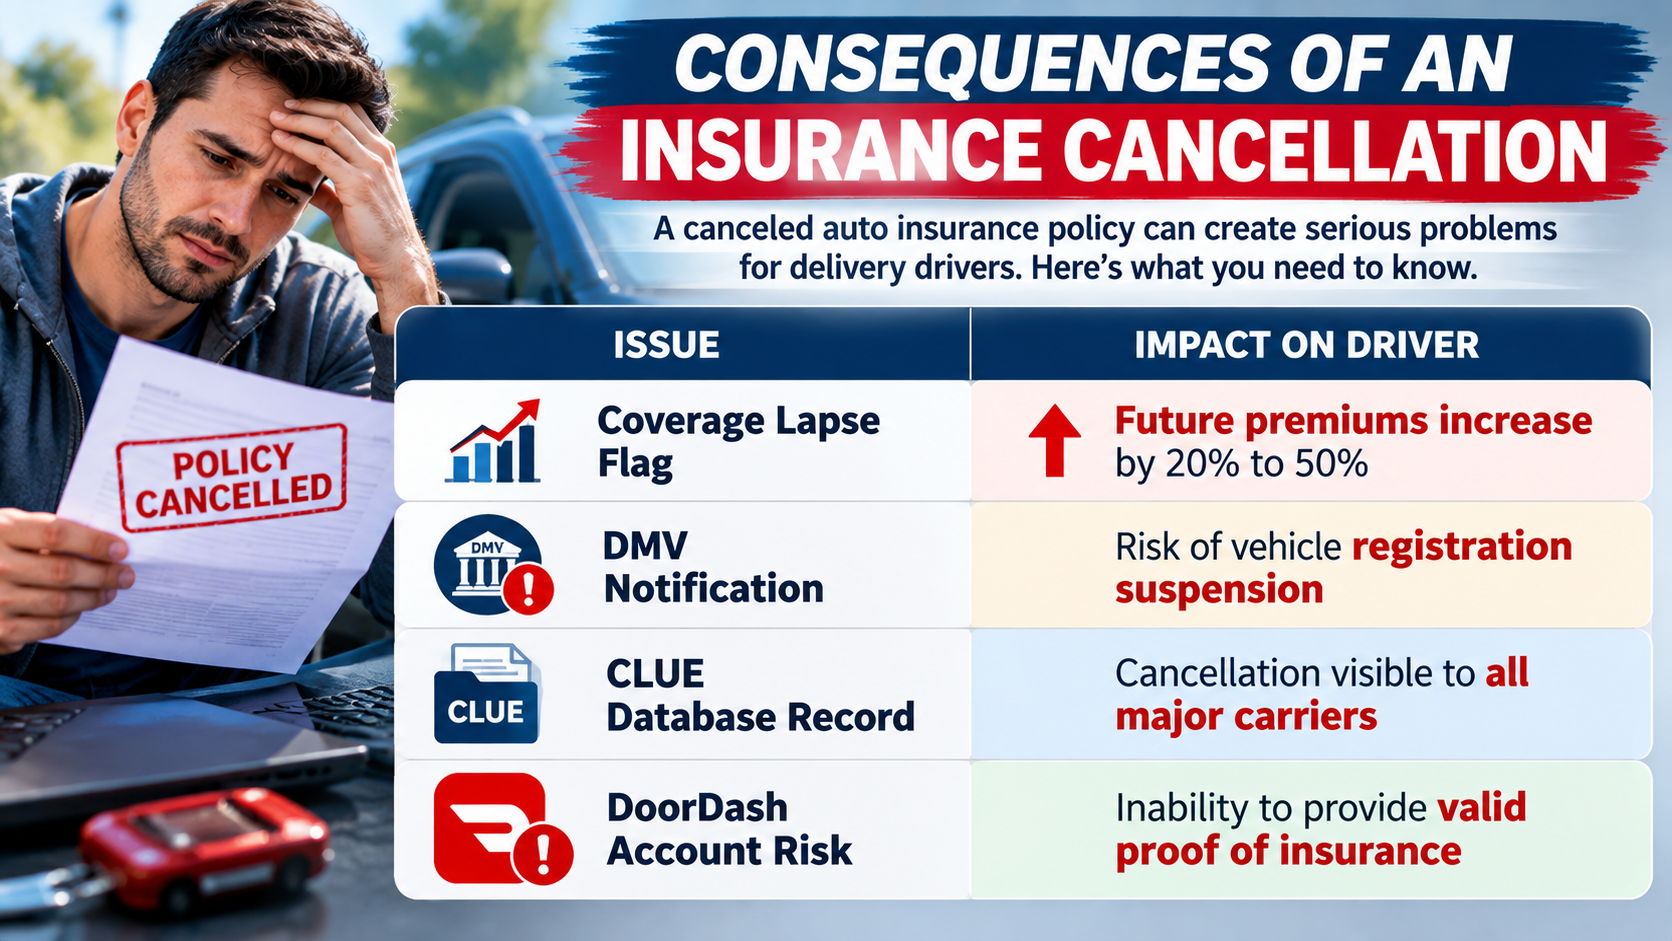
Finding out that your auto insurance policy was canceled or non-renewed because you deliver for DoorDash is a stressful, high-urgency situation. Major insurance carriers routinely monitor commercial activity, and failing to declare food delivery work is considered a violation of policy terms—often flagged as material misrepresentation.
Driving without insurance is illegal in almost every U.S. state, and a lapse in coverage can lead to suspended driver’s licenses, heavy fines, and permanently inflated insurance rates.
If your insurance company dropped you after discovering your DoorDash activity, do not panic. Follow this step-by-step recovery guide to secure legal coverage immediately and protect your livelihood.
Why Insurance Companies Cancel Policies for DoorDash Drivers
Standard personal auto insurance policies strictly exclude commercial or business activities. When an insurer discovers you deliver food for DoorDash (often after an accident investigation, toll audit, or mileage inspection), they view it as un-underwritten risk.
Insurers typically take one of two actions:
- Immediate Policy Cancellation: Issued if the company suspects fraud or intentional non-disclosure during a claim.
- Notice of Non-Renewal: The insurer allows your policy to run until its expiration date but refuses to renew it for another term.
What to Do Immediately If Your Policy Is Canceled (5 Steps)
Step 1: Check Your Official Notice Date
Insurance companies are legally required to give written notice before terminating a policy (usually 10 to 30 days depending on your state). Identify your exact effective cancellation date so you know how many days you have to secure a new policy before experiencing a legal coverage lapse.
Step 2: Stop Delivering for DoorDash Temporarily
Do not drive for DoorDash or any other gig platform if your policy has already expired or is about to expire within 24 hours. Driving uninsured exposes you to personal financial liability for all damages and criminal penalties.
Step 3: Shop for Gig-Friendly Insurance Carriers
Not all insurance providers reject delivery drivers. Look for companies that actively offer food delivery endorsements or business-use add-ons.
Top options for DoorDash drivers include:
- Progressive: Highly accommodating to gig drivers with affordable delivery riders.
- State Farm: Offers flexible business-use endorsements through local agents.
- Allstate & GEICO: Offer specialized rideshare/delivery add-ons in most states.
Step 4: Be 100% Honest on Your New Application
When applying for a new policy, always disclose that you deliver for DoorDash. Lying on a new application after a cancellation will only lead to another immediate cancellation and potential blacklisting in insurance databases.
Step 5: Upload Your New Insurance Card to DoorDash
Once your new policy is active, immediately upload your updated insurance card to your DoorDash Dasher app dashboard to maintain your driver status without interruption.
How to Get Auto Insurance After Being Dropped
If standard insurance companies refuse to quote you due to a recent cancellation on your record, consider these specialized solutions:
- Non-Standard Auto Insurance Providers: Companies like The General, Dairyland, or National General specialize in high-risk drivers and individuals with coverage gaps or prior cancellations.
- State Assigned Risk Plans: If you are denied by multiple private insurers, every U.S. state operates a high-risk auto insurance pool to ensure drivers can obtain minimum legal coverage.
Frequently Asked Questions (FAQ)
Will a policy cancellation affect my DoorDash account?
DoorDash requires proof of valid auto insurance to keep your account active. If your policy is canceled and you fail to upload a valid replacement, your Dasher account will be paused or deactivated during routine document reviews.
How long does a cancellation stay on my insurance record?
A policy cancellation or non-renewal stays recorded in the CLUE (Comprehensive Loss Underwriting Exchange) database for 3 to 5 years.
Can DoorDash pay for my car repairs if my personal insurance drops me?
No. DoorDash’s excess commercial insurance only provides third-party liability protection during active deliveries. It does not cover physical damage to your vehicle if your personal insurer denies the claim.
Summary Action Plan
Having your insurance canceled due to DoorDash is a major setback, but it is entirely fixable:
- Identify your exact policy expiration date.
- Get quotes from gig-friendly carriers like Progressive or State Farm.
- Explicitly declare your delivery work to get a valid policy with a delivery rider.