If you are delivering food for DoorDash in Texas, there is a critical insurance gap you need to know about before hitting the road. Millions of gig workers assume their standard personal car insurance policy fully protects them while making deliveries. Unfortunately, discovering the truth after an accident can lead to denied claims, canceled policies, and severe out-of-pocket financial losses.
In this guide, we break down Texas auto insurance laws for DoorDash drivers, how commercial exclusions work, and exactly what coverage you need to protect your vehicle and livelihood.
The Short Answer: No, Standard Personal Insurance Does Not Cover DoorDash
In Texas, standard personal auto insurance policies explicitly exclude business and commercial activities, including food delivery and rideshare services.
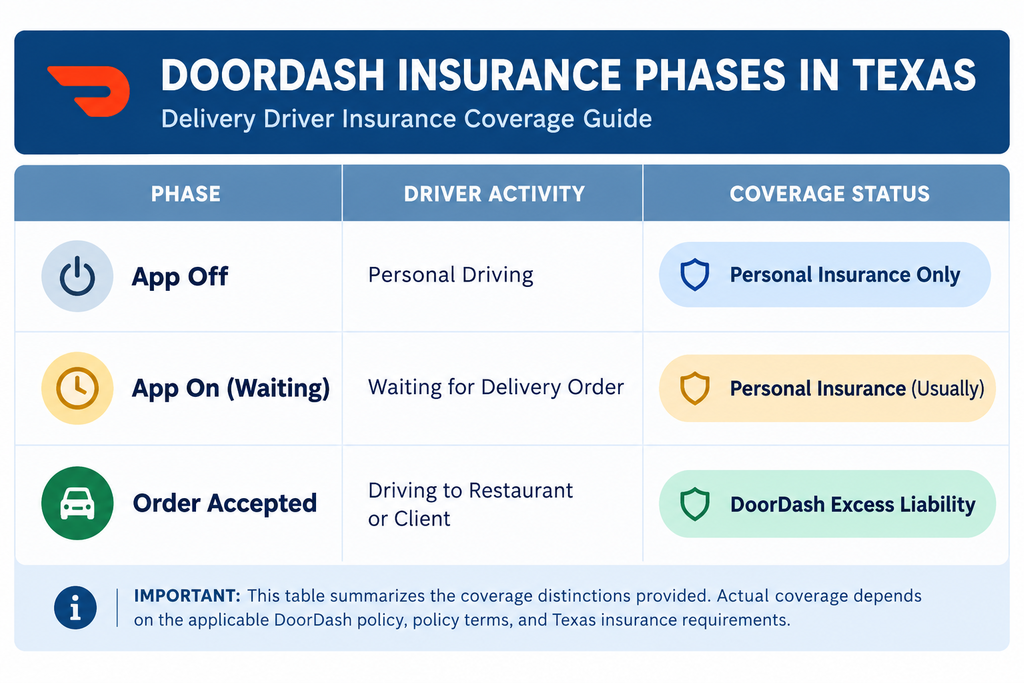
When you turn on the DoorDash app and accept a delivery order, your vehicle transitions from personal use to commercial use. If you get into an accident while delivering food and only carry a personal auto policy, your insurance company will almost certainly deny your claim.
Furthermore, failing to inform your insurance provider that you deliver for DoorDash can be flagged as material misrepresentation, which may lead to the immediate cancellation of your policy.
How DoorDash’s Excess Insurance Works in Texas
DoorDash does provide contingent liability insurance for its drivers in Texas, but it comes with strict limitations and conditions:
- Active Delivery Phase Only: DoorDash’s coverage is only active from the moment you accept an order until the food is delivered or the order is canceled.
- Excess Coverage Only: DoorDash’s policy acts as excess coverage. This means it only kicks in after your personal insurance policy formally denies the claim.
- Property Damage Exclusions: DoorDash’s liability insurance covers damage or injuries you cause to other people (third-party liability). It does not cover damage to your own vehicle, regardless of who was at fault.
What Happens If You Get in an Accident While Delivering in Texas?
If you are involved in a crash while making a DoorDash delivery in Texas without proper coverage, here is the typical scenario:
- Step 1: The police report notes that you were driving for a delivery service.
- Step 2: You file a claim with your personal insurance carrier.
- Step 3: The insurer discovers the delivery activity and issues a formal claim denial based on the commercial use exclusion.
- Step 4: You are left responsible for paying for repairs to your own car out of pocket.
- Step 5: DoorDash’s excess insurance may cover the third-party damages, but you may still face policy cancellation from your personal provider.
How to Get Properly Covered as a DoorDash Driver in Texas
Protecting yourself does not necessarily require buying an expensive, full commercial auto insurance policy. Most major insurance providers in Texas offer affordable solutions tailored for delivery drivers:
1. Add a Business Use or Delivery Endorsement
Many top insurers in Texas (such as State Farm, Progressive, and Allstate) allow you to add a Rideshare or Food Delivery Endorsement (rider) to your existing personal policy. This add-on fills the gap between your personal policy and DoorDash’s liability coverage.
- Average Cost: Adding a delivery endorsement typically adds $15 to $40 per month to your existing premium.
2. Commercial Auto Insurance
If you drive full-time or use a specialized vehicle (like a cargo van or commercial pickup), a commercial auto policy provides comprehensive protection for both liability and physical damage to your vehicle at all times.
Frequently Asked Questions (FAQ)
Does DoorDash know if I have the right insurance in Texas?
DoorDash requires you to submit proof of valid auto insurance when you sign up. However, they do not verify whether your specific policy includes a commercial or food delivery endorsement. Ensuring you have the correct coverage is your legal and financial responsibility.
Will my insurance company find out I was delivering for DoorDash?
Yes. Insurance adjusters investigate accidents thoroughly. They inspect police reports, check vehicle contents, and may ask directly if you were logged into a delivery app during the crash.
Is rideshare insurance the same as food delivery insurance in Texas?
Not always. Some companies bundle rideshare (Uber/Lyft) and food delivery (DoorDash/UberEats) into one endorsement, while others require separate add-ons. Always confirm with your insurance agent that food delivery is explicitly included.
Summary & Recommendation
Driving for DoorDash in Texas without notifying your insurance provider carries significant financial risk. To avoid denied claims and costly out-of-pocket expenses:
- Contact your insurance agent and ask if they offer a food delivery or business use endorsement.
- Compare quotes from providers in Texas that are friendly to gig workers (such as Progressive or State Farm).
- Ensure your policy covers physical damage to your vehicle while the DoorDash app is active.