Operating as an independent contractor with a Sprinter van or cargo van can be a lucrative business in the freight and courier delivery industry. Whether you carry loads for Amazon Relay, regional expeditors, or local clients, securing proper commercial auto insurance is your single largest fixed operating expense.
Because Sprinter vans are larger, heavier, and carry higher liability risks than standard personal vehicles, personal auto policies will not cover them for business use.
In this complete breakdown, we examine average Sprinter van insurance costs for independent drivers, key factors that influence your rates, and practical strategies to lower your monthly premiums.
How Much Does Sprinter Van Insurance Cost per Month?
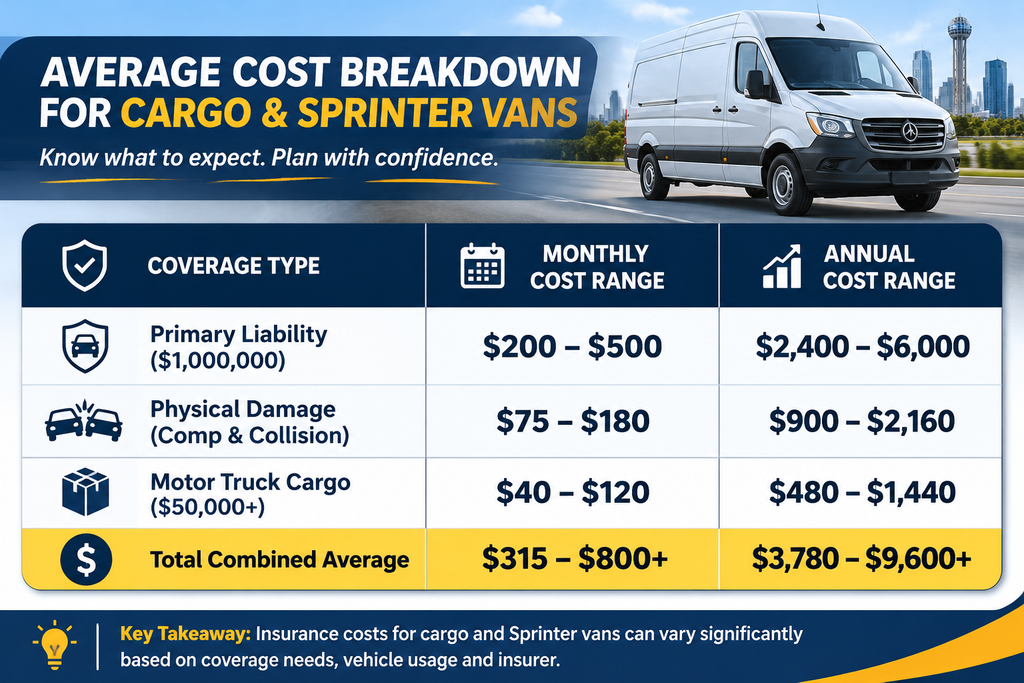
For an independent driver operating a Sprinter or high-roof cargo van in the United States, the average cost of commercial auto insurance ranges from $250 to $650 per month ($3,000 to $7,800 annually) for standard primary liability and physical damage coverage.
However, if you operate under your own authority (DOT/MC number) or carry specialized cargo, costs can range between $700 and $1,200+ per month, depending on coverage limits and load requirements.
Key Insurance Coverages Required for Independent Van Drivers
When setting up your commercial policy, delivery contracts (such as Amazon Relay or courier brokers) usually dictate minimum required coverage tiers:
1. Primary Auto Liability
This is mandated by law and covers bodily injury and property damage you cause to others in an accident. Most expediting brokers require a minimum liability limit of $1,000,000.
2. Physical Damage Coverage
This protects your actual Sprinter van against losses from crashes, theft, fire, or severe weather.
- Collision: Pays for repairs if your van hits another vehicle or object.
- Comprehensive: Covers non-collision incidents such as vandalism, windstorm damage, or windshield cracks.
3. Motor Truck Cargo Insurance
If you haul goods for paying customers or platforms, cargo insurance protects the shipment inside your van. Minimum requirements typically range from $25,000 to $100,000 depending on the payload value.
4. Non-Trucking Liability (Bobtail Insurance)
If you are leased onto a larger motor carrier, this covers your vehicle when you are driving the Sprinter van for personal use outside of active dispatch work.
5 Major Factors That Impact Your Premium Rates
Insurance underwriters calculate commercial rates for Sprinter vans based on several specific risk variables:
- Driving History & MVR: A clean Motor Vehicle Record with no at-fault accidents or moving violations over the last 3 to 5 years is critical for lower premiums.
- Operating Radius: Local delivery routes (under 100 miles) carry significantly lower risk and lower insurance rates compared to regional or regional over-the-road (OTR) long-haul expediting.
- Vehicle GVWR & Value: High-roof, extended-wheelbase Sprinter vans with higher Gross Vehicle Weight Ratings cost more to insure than standard light-duty panel vans.
- Years in Business / Commercial Experience: New independent contractors with zero business history pay higher rates during their first 12 to 24 months.
- Location & Garage Zip Code: Metro areas with dense traffic, high accident rates, or elevated vehicle theft statistics (e.g., Los Angeles, Chicago, Miami) have higher baseline premiums.
How to Lower Your Sprinter Van Insurance Premiums
If high insurance costs are compressing your profit margins as an independent driver, use these actionable tactics to reduce your monthly expenses:
- Increase Your Deductibles: Raising your physical damage deductible from $500 to $1,000 or $2,500 can lower your monthly premium by up to 15% to 20%.
- Install Dashcams & Telematics: Insurers like Progressive and National General offer commercial discounts for drivers who use telematics devices or commercial dash cameras to verify safe driving behavior.
- Pay Annually or Semi-Annually: Paying your total premium upfront eliminates installment fees and earns a discount from most insurance carriers.
- Bundle Business Policies: If you operate multiple vans or maintain a general liability policy, bundling coverages with the same provider lowers overall costs.
Frequently Asked Questions (FAQ)
Can I insure a Sprinter van under a personal auto insurance policy?
No. Insurance companies classify Sprinter vans used for commercial transport, freight hauling, or courier work as commercial vehicles. Claims filed under personal policies for business activities will be denied.
What insurance is required for Amazon Relay cargo van drivers?
Amazon Relay generally requires independent contractors to carry $1,000,000 in Commercial Auto Liability, $50,000 in Motor Truck Cargo coverage, and Workers’ Compensation or Occupational Accident insurance where applicable.
Is Progressive good for commercial Sprinter van insurance?
Progressive Commercial is currently one of the largest providers for independent cargo van drivers in the U.S. They offer flexible coverage options, business use add-ons, and telematics discounts tailored for single-vehicle operations.
Conclusion & Next Steps
Insurance is a non-negotiable cost of doing business as an independent Sprinter van driver. To secure the best rates:
- Gather quotes from at least three commercial auto carriers specializing in light commercial vehicles.
- Review contract requirements from your freight brokers before setting coverage limits.
- Maintain a clean driving record and implement safety equipment to maintain low renewal rates